Insurers have been challenged to move beyond traditional insurance products and play a bigger role in supporting investment, infrastructure, production and other areas of Uganda’s economic transformation in the wake of the implementation of the 10-fold growth framework.
According to the National Planning Authority Executive Director, Dr. Joseph Muvawala, insurance should be part of the institutional architecture that makes economic growth possible and thus urged the insurance industry to position itself to support the anticipated growth.
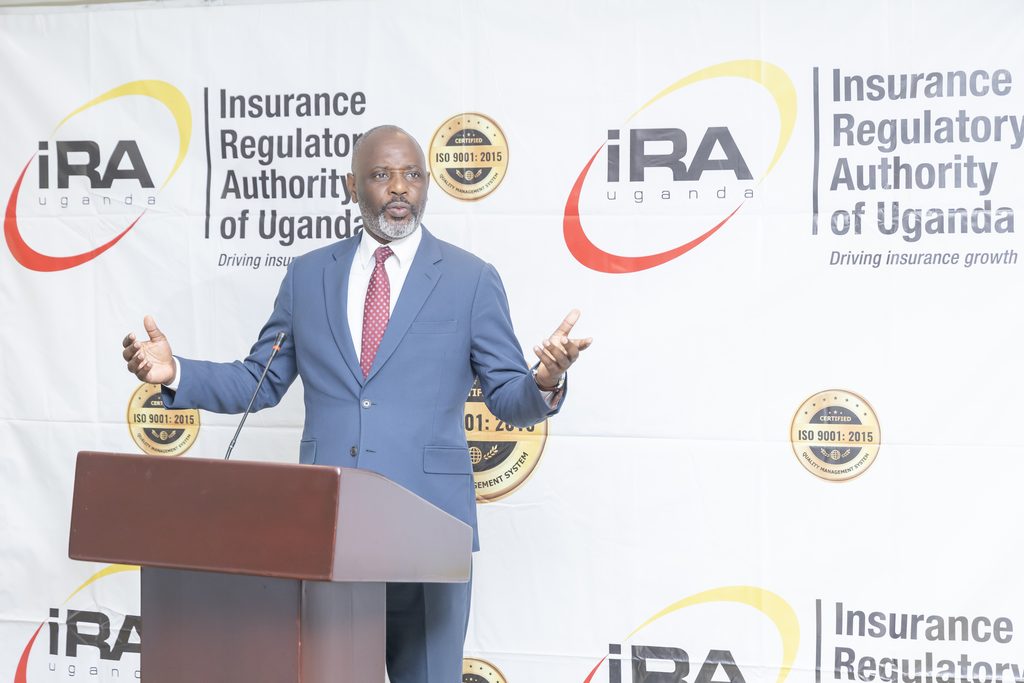
Dr. Muvawala who was speaking at 69th CEOs Breakfast Meeting organized by the Insurance Regulatory Authority of Uganda (IRA) in Kampala on September 23, 2026, said Uganda’s 10- fold growth target would require major investments in infrastructure, agro-industrialization, tourism development, mineral development, technology and innovation especially through creatives. Such investments, he said, will create a much greater need for insurance to manage associated risks.
“Insurance is not a service that becomes relevant after growth has occurred. It is part of the institutional architecture that makes growth possible,” Dr. Muvawala said.
Uganda’s $500 billion ambition
The Ten-Fold Growth framework aims to increase Uganda’s economy from about US$50 billion in 2023 to US$500 billion by 2040.
Dr. Muvawala, however, expressed concern that Uganda’s insurance industry remains relatively small compared with the size of the economy and the scale of investment planned under the Fourth National Development Plan (NDP IV).
He noted that while the industry’s gross written premiums reached Shs2.02 trillion in 2025 and claims paid stood at Shs778.9 billion, penetration remains low, at about 0.8% of the Gross Domestic Product, and that only about 2.27 million people, representing 5.04% of Uganda’s population, had insurance cover.
“About 95 out of every 100 Ugandans remain outside formal insurance protection. This means that most households, farmers and small businesses still have to deal with losses using their incomes and savings, selling assets or relying on public support,” he said.
He challenged insurers to look beyond premium growth when measuring the performance of the industry, noting that a truly growing and well performing insurance market should also reach new customers and provide protection to households and businesses that have traditionally been underserved.
“Are we extending protection beyond Kampala? Are we designing products for irregular incomes? Are we serving the informal economy, where most Ugandans earn their livelihoods?” he asked.
ATMS will drive insurance demand
He noted that the Government’s four priority growth areas – Agro-industrialisation, Tourism Development, Minerals Development including oil and gas, and Science, Technology and Innovation (ATMS), are expected to generate substantial new demand for insurance requiring that industry players to strategize and tap into this growth.
He said agro-industrialization will require insurance cover for crops, livestock, irrigation equipment, warehouses, processing facilities, cargo and business interruption while tourism is expected to create demand for property, travel, aviation, marine, public-liability and event insurance.
Additionally, oil and gas sector will require specialised engineering, environmental-liability, equipment, cargo and operational-risk cover, while the technology sector will increasingly require cyber insurance, data-protection cover, professional indemnity and technology-related liability products.
He, however, noted that the opportunity extends beyond the ATMs, saying that major investments in energy, transport, manufacturing, urban infrastructure and regional trade will generate demand for construction and engineering insurance, catastrophe protection, property cover, business interruption, marine, export-credit and political-risk insurance.
“Insurers should begin designing integrated solutions for complete value chains rather than offering isolated policies for individual assets,” Dr. Muvawala said.
Agriculture needs more intervention
Dr. Muvawala applauded Government on the introduction of the Shs5 billion Uganda Agriculture Insurance Scheme for farmers to access insurance at a subsidized rate, but noted that though it has demonstrated its financial value, it is yet to achieve its full developmental purpose.
He noted that the said that the Scheme is not sufficiently reaching the farmers for whom the highest subsidy was intended. He urged players to ensure that the scheme moves beyond farm-level cover to protect the entire agricultural value chain – from production and aggregation to storage, processing, transportation, export and payment.
He also pledged to support the industry in lobbying Government to increase the subsidy to benefit more farmers, explaining that the existing allocation is small relative to the size of Uganda’s agricultural sector and the range of risks it faces.
The IRA Ag. Chief Executive Officer, Dr. Protazio Sande called on players to prepare to tap into the immense opportunities presented in the various sectors, saying that the industry must ensure that all Uganda’s developmental aspirations do not go unprotected.
“Insurers, let us not wait to benefit from the growth, we should facilitate this growth,” he emphasized.
He applauded Dr. Muvawala for committing to front insurance in the national planning framework as a risk management tool given that it is critical for any sustainable development agenda.